Last updated 10 November 2026 · Facts checked on mof.gov.ae and tax.gov.ae on 10 November 2026
The short answer
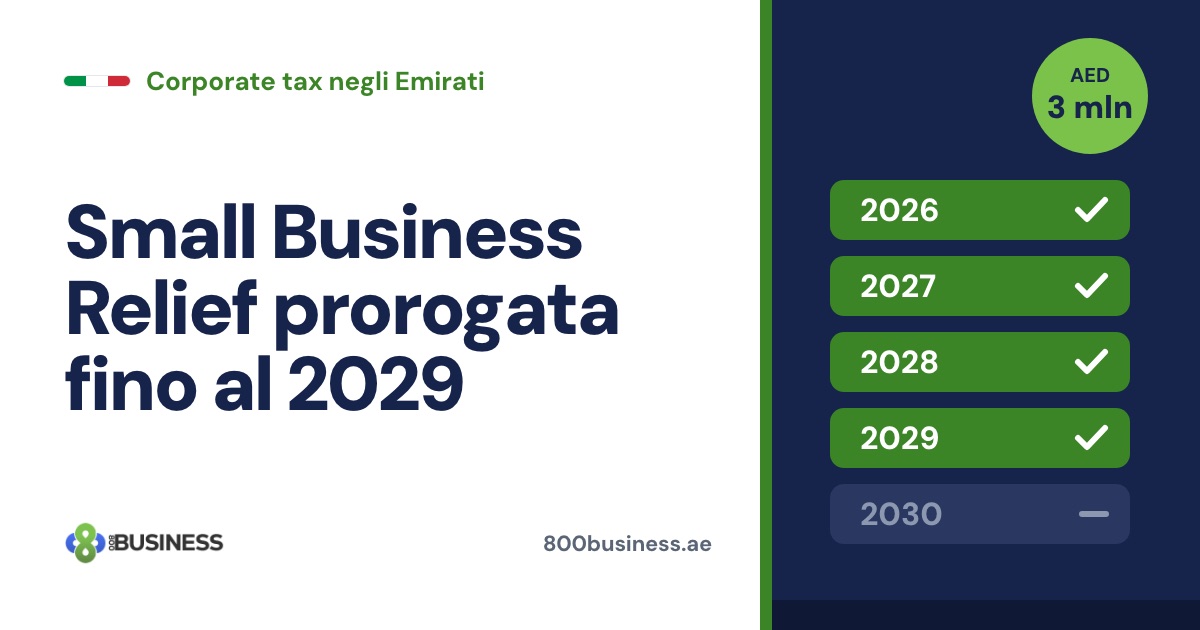
Yes, Small Business Relief still applies in 2027. Ministerial Decision No. 131 of 2026 extends it to tax periods ending on or before 31 December 2029. It used to end with periods ending on 31 December 2026. The revenue limit is unchanged at AED 3 million per tax period. You still have to register, file a corporate tax return and elect the relief on each return (Ministry of Finance, 7 August 2026, checked 10 Nov 2026).
What changed, in one table
| Before (MD 73 of 2023) | Now (MD 131 of 2026) | |
|---|---|---|
| Last tax period covered | Periods ending on or before 31 December 2026 | Periods ending on or before 31 December 2029 |
| Revenue limit | AED 3,000,000 | AED 3,000,000 (unchanged) |
| Decision date | 2023 | Dated 29 July 2026, announced 7 August 2026 |
The FTA's Small Business Relief guide from August 2023 still shows 31 December 2026. That date is out of date. Many articles online still repeat it.
What it means for your returns
For a company with a 31 December year end:
| Tax period | Return and payment due | Small Business Relief? |
|---|---|---|
| 1 Jan – 31 Dec 2026 | 30 September 2027 | Yes, if revenue ≤ AED 3m and you elect it |
| 1 Jan – 31 Dec 2027 | 30 September 2028 | Yes, if revenue ≤ AED 3m and you elect it |
| 1 Jan – 31 Dec 2028 | 30 September 2029 | Yes, if revenue ≤ AED 3m and you elect it |
| 1 Jan – 31 Dec 2029 | 30 September 2030 | Yes, the last one |
| 1 Jan – 31 Dec 2030 | 30 September 2031 | No (unless extended again) |
Different year end? The test is when the tax period ends. A period from 1 July 2029 to 30 June 2030 ends after 31 December 2029, so it is not covered.
The return deadline (9 months after the year end) comes from the Corporate Tax Law and the FTA's deadline releases (FTA, checked 10 Nov 2026).
Who can use it
- Resident persons, meaning UAE companies and individuals doing business in the UAE.
- Revenue of AED 3 million or less in the tax period and in every earlier tax period. Go above it once and you can't come back in later years.
- Not for Qualifying Free Zone Persons. A Free Zone company claiming the 0% rate on qualifying income can't also elect Small Business Relief.
- Not for members of large multinational groups (consolidated group revenue of more than AED 3.15 billion).
Sources for these conditions: Article 21 of the Corporate Tax Law, Ministerial Decision No. 73 of 2023 as amended by MD 131 of 2026, and the FTA's Small Business Relief page (checked 10 Nov 2026).
What you give up when you elect it
Small Business Relief treats you as having no taxable income for that period. In return, the law switches off tax-loss relief, exempt income, other reliefs and deductions for that period (Article 21(2) of the Corporate Tax Law). In practice:
- Losses from that period can't be carried forward to later years.
- Disallowed net interest from that period can't be carried forward either.
- You don't need transfer pricing documentation, but deals with related parties must still be at market price, according to the FTA.
- You file a simpler return, but you still keep proper books. The FTA can ask for records to check that you qualify (Article 21(3)).
If you expect losses this year and profits later, electing relief may not be the best choice. Look at the numbers first.
Free Zone company: relief or Qualifying Free Zone Person?
Many of our clients have a Free Zone company with revenue under AED 3 million. They can choose:
| Small Business Relief | Qualifying Free Zone Person | |
|---|---|---|
| Who | Revenue ≤ AED 3m | Free Zone company meeting all the QFZP conditions |
| Corporate tax | No tax for the period | 0% on qualifying income, 9% on the rest |
| Audited accounts | Not required for the relief itself (your Free Zone may still ask for financial statements to renew the licence) | Required |
| Ends | Periods ending by 31 Dec 2029 | No end date |
Which one is better depends on your activity, your clients (mainland or abroad) and your plans. We look at it case by case.
Frequently asked questions
Do I still have to register for corporate tax? Yes. The relief is chosen in the return, so you must be registered and file every year.
Is Small Business Relief automatic? No. You tick the election on each return. If you don't, normal rules apply: 0% on the first AED 375,000 of taxable income and 9% above.
Does it change VAT or e-invoicing? No. VAT registration (over AED 375,000 of taxable supplies) and e-invoicing (go-live on 1 July 2027 for businesses under AED 50 million) are separate rules.
What if my revenue is AED 3.2 million in 2027? You lose the relief for 2027 and for all later periods, even if revenue drops again.
Can it be extended again after 2029? Only by a new Ministerial Decision. We will update this page if that happens.
Not sure relief is right for your company?
In a free 30-minute Zoom call we look at your revenue, your Free Zone status and your year end, and tell you whether to elect Small Business Relief or go another route. Accounting clients get our Zero Penalty Guarantee: if you get an FTA penalty for a deadline we were responsible for, we pay it, as long as you send your documents by the 10th of each month. We prepare your return and send it to you for approval before anything goes to the FTA.
Book my free 30-minute call · Message us on WhatsApp: +971 52 713 7661
Also useful: Corporate tax in the UAE · How Small Business Relief works · UAE tax deadlines 2027 · Accounting services in Dubai
Sources
All sources checked on 10 November 2026.
- Ministry of Finance, Ministry of Finance announces extension of Small Business Relief for Corporate Tax purposes until 31 December 2029 (7 August 2026): MD No. 131; tax periods ending on or before 31 December 2029; AED 3 million threshold
- Ministry of Finance, Ministerial Decision No. 131 of 2026 (PDF): replaces article 2(2) of MD 73/2023
- Ministry of Finance, Federal Decree-Law No. 47 of 2022 on Corporate Tax: article 21 (Small Business Relief), articles 48 and 53 (9-month deadline)
- Federal Tax Authority, FY2025 corporate tax deadline release: the 9-month rule applied
- Ministry of Finance, Federal Decree-Law No. 47 of 2022 and its amendments, consolidated (January 2026): article 21(2) (no tax-loss relief, reliefs or deductions in a relief period), article 21(3), article 54 (audited statements only where a Ministerial Decision requires them)
- Federal Tax Authority, Small Business Relief: who can elect, excluded QFZPs and multinational group members above AED 3.15 billion, no transfer pricing documentation
Update when: the FTA publishes a new Small Business Relief guide, or the AED 3 million limit or the exclusions change.
Next step: Accounting services in Dubai